
Table of contents

TL;DR
Across 25+ VC and private equity AGM presentations we designed last year, decks ran from 60 to 130+ slides. Length varied. The problems did not. Five patterns repeated in every clear deck.
Last year alone, we designed and supported more than 25 VC and private equity AGM presentations, ranging from approximately 60 to more than 130 slides.
A fund AGM is the annual meeting where a general partner gives limited partners a consolidated view of fund performance, portfolio progress, liquidity, market conditions, lessons learned and priorities for the year ahead. Unlike a statutory shareholder AGM, the purpose is primarily LP communication, transparency and context.
Across those projects, no two AGM presentations followed exactly the same structure. But the strongest consistently solved the same communication challenges.
What Should a VC or Private Equity AGM Presentation Include?
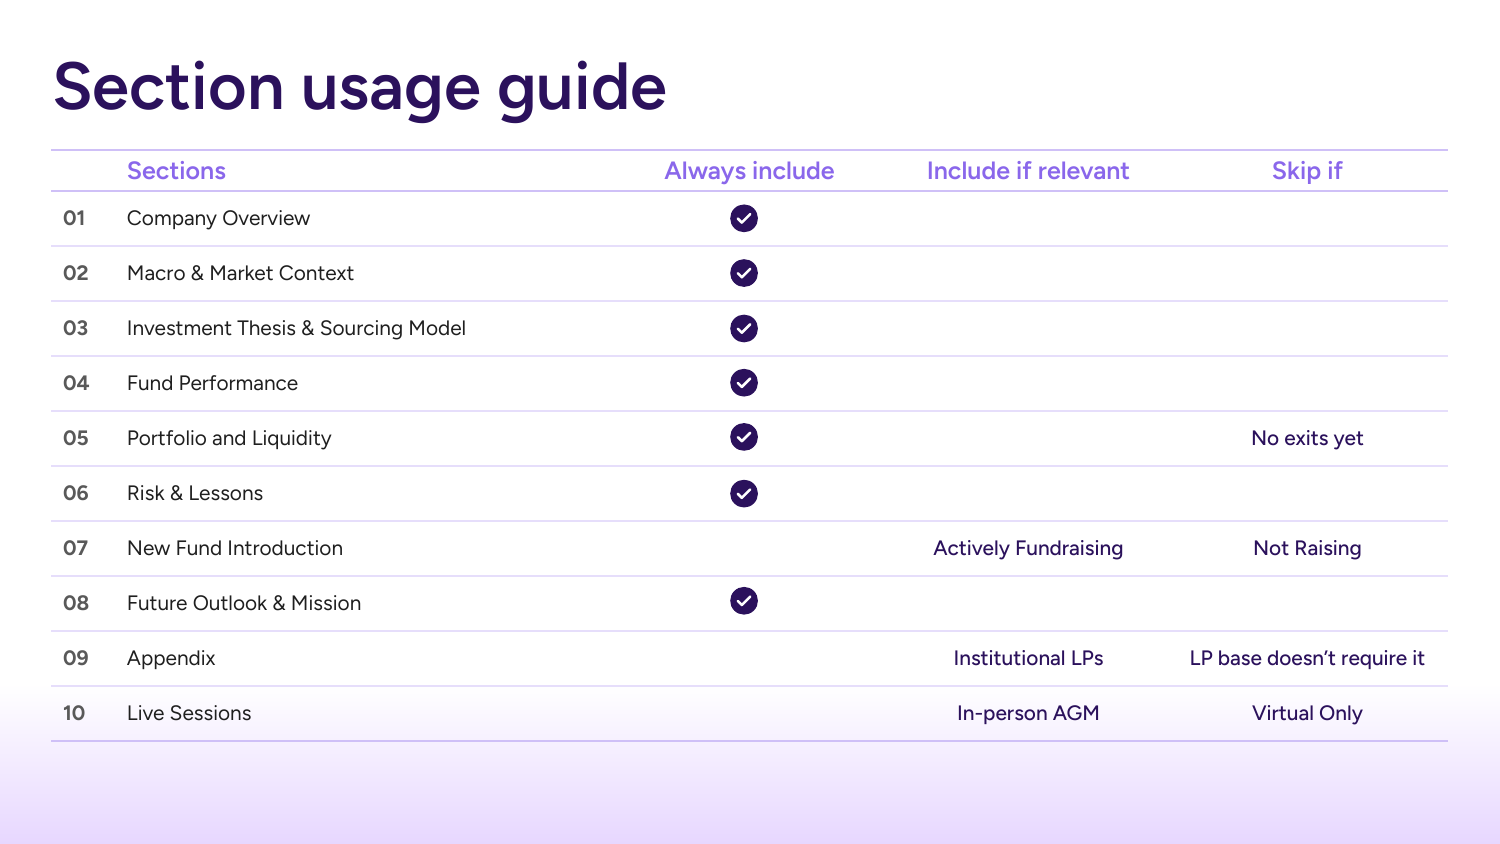
Most AGM presentations include a year-in-review, firm update, market context, investment thesis and sourcing, fund performance, portfolio developments, liquidity activity, risks and lessons learned, and forward outlook.
Detailed company information, valuation methodology and supporting financial data generally belong in the appendix. New-fund sections and live-event AGM slides should only appear when relevant.
There is no ideal slide count. In our experience, decks range from roughly 60 to 130+ slides, depending on the number of funds, portfolio companies and speakers.
Planning should typically begin four to six weeks before the AGM. For 100-plus-slide presentations with several contributors, allow six to eight weeks.
Building one now? See how we approach VC and private equity presentation design.
1. Company Overview Slides Establish the Design System
The opening usually includes a Year in Review, Firm at a Glance and Team.
This is where the grid, typography, metric treatments, image style and navigation should be locked in. When content later arrives from Investor Relations, finance, investment partners, operating teams and portfolio companies, a defined system keeps the AGM presentation slides consistent.
Locking this system early makes a large deck easier to scale when different teams are contributing content.
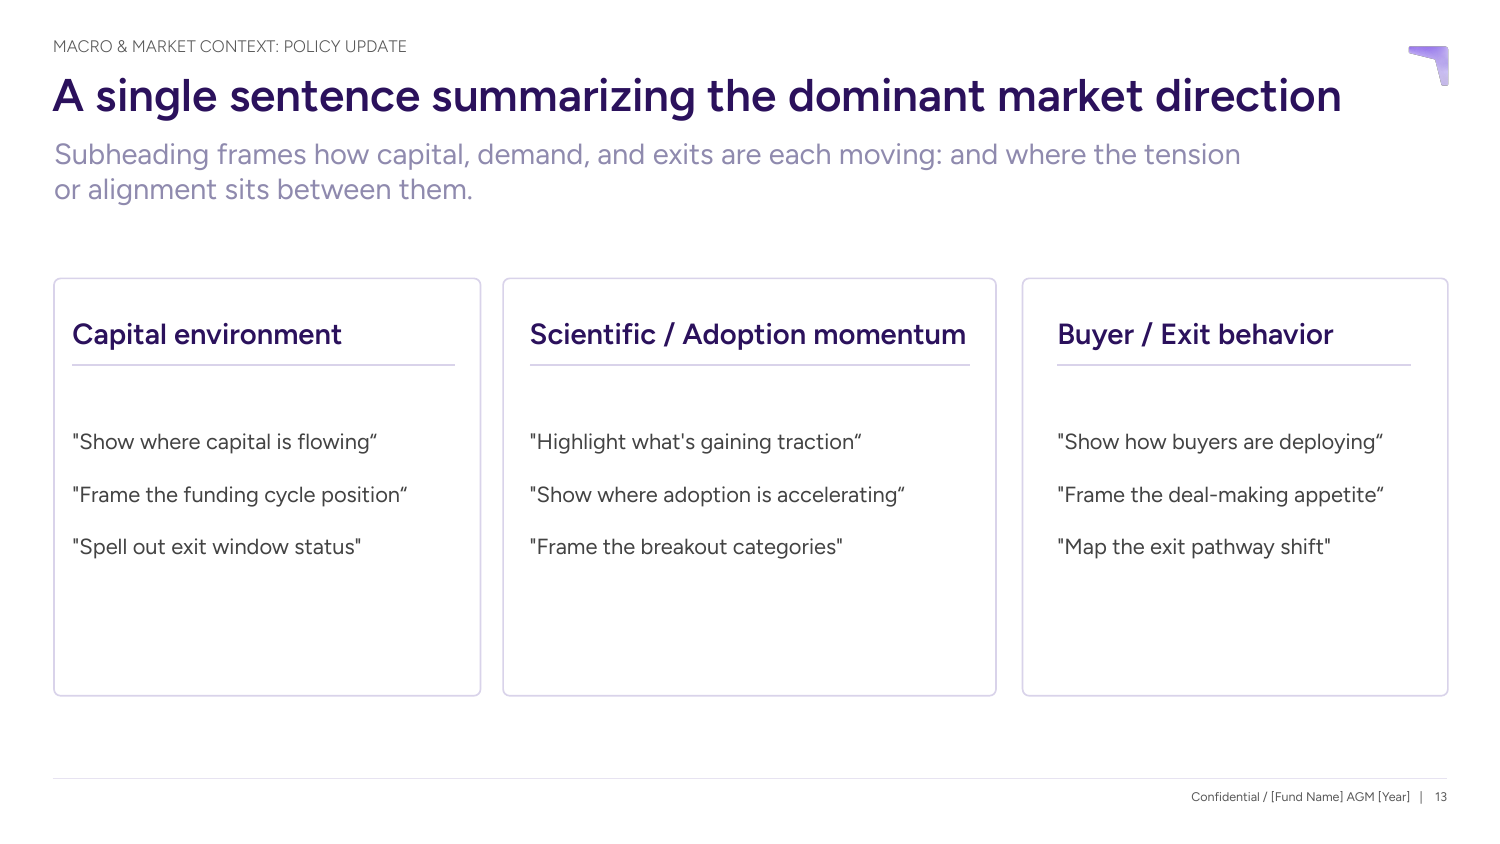
2. Market Context Should Lead Directly to Investment Strategy
Market sections are most useful when they eexplain a decision, not simply what happened externally.
Policy changes, funding conditions, sector trends and geographic shifts should connect directly to how the GP is adjusting deployment, sourcing or portfolio management.
A useful structure is:
market signal → implication → fund response
The same principle applies to thesis and sourcing slides. Process diagrams, investment funnels and quantified proof points usually communicate a repeatable investment system more clearly than paragraphs of positioning language.
3. Fund Performance Slides Should Explain What Drove the Numbers
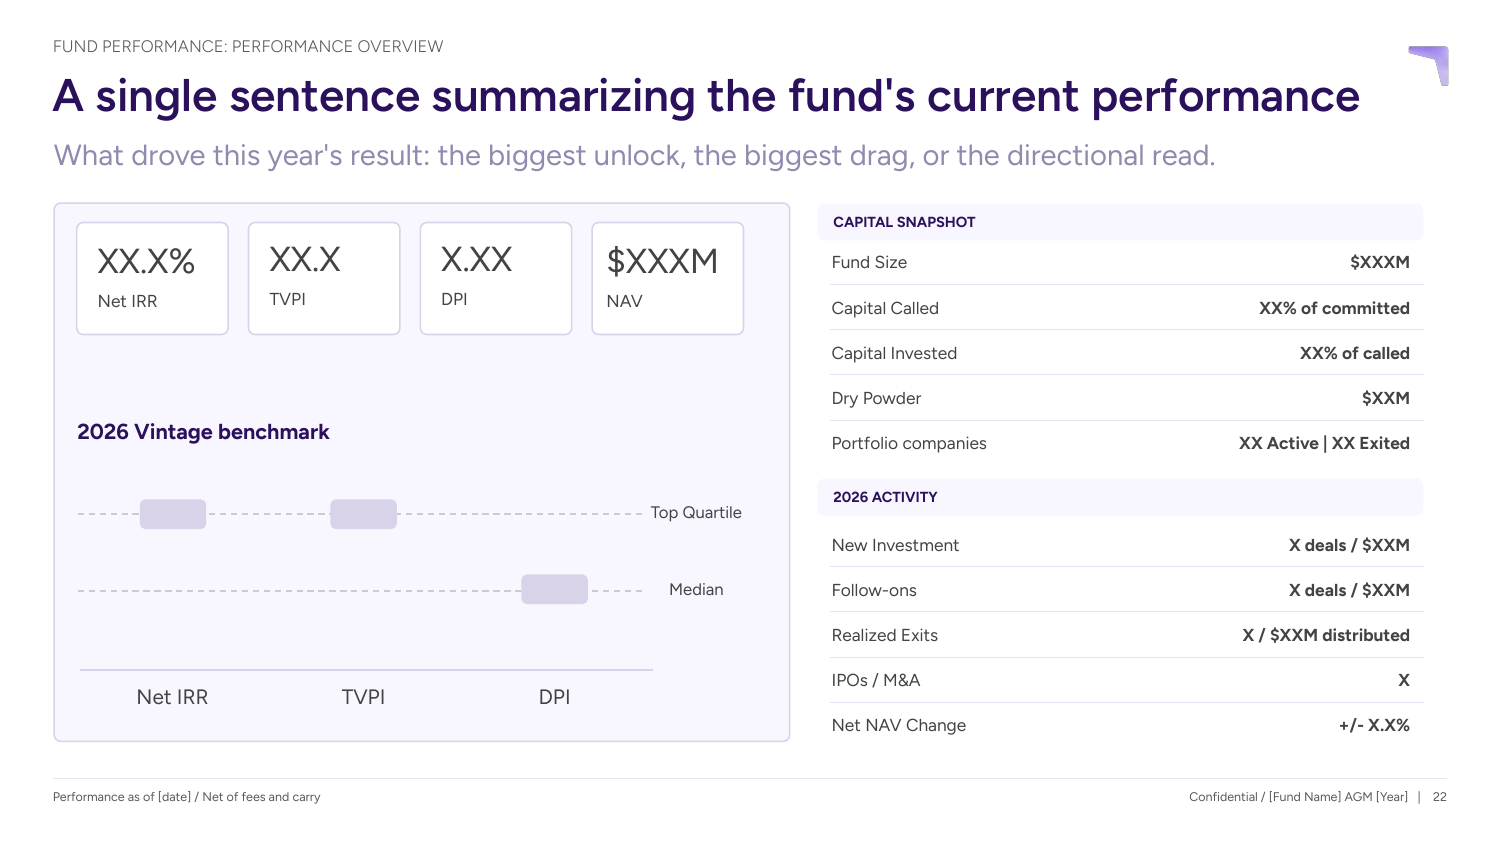
An effective AGM presentation does more than display Net IRR, TVPI, DPI and NAV.
Start with the overall performance posture and explain what changed: a markup, exit, deployment decision, valuation movement or portfolio drag.
Then use a consistent per-fund framework across vintages so LPs can compare results without relearning the layout. Benchmark charts, NAV bridges and capital-versus-reserve visuals often communicate movement more effectively than dense tables.
Detailed fund accounts and valuation support can remain in the appendix.
4. Portfolio, Liquidity and Risk Need Repeatable Frameworks
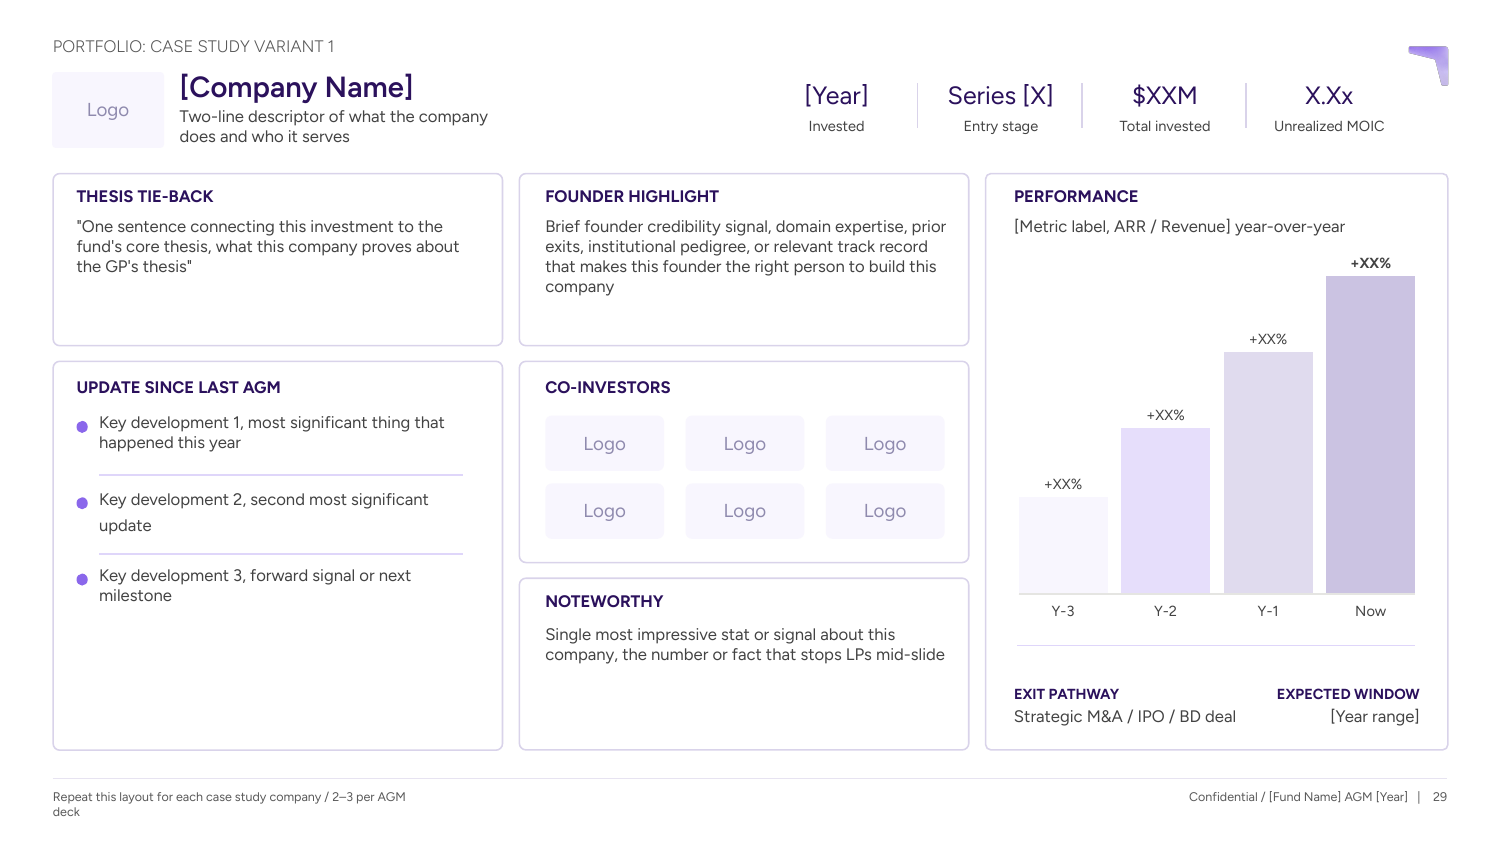
Portfolio-company updates become difficult to follow when every company uses a different structure.
Keep entry stage, capital invested, ownership, major milestones, performance and outlook in consistent locations. Then change the central visual according to the company story, revenue growth, clinical progress, operational improvement or exit readiness.
Liquidity slides should answer what has been realized, what has reached LPs and what may come next.
Risk slides should go one step further: what happened → what the GP learned → what changed as a result.
5. AGM Production Needs One System and One Owner
The biggest AGM challenge is often coordination rather than slide design.
Investor Relations, finance, investment partners, operating teams and portfolio companies may all contribute to the same annual general meeting presentation.
A single project owner should control the master deck, deadlines, review rounds and final QA. Repeatable layouts reduce fragmentation and make late changes safer.
Optional modules, such as a new fund introduction, founder panel or fireside chat, should fit the same system rather than feel like separate presentations added at the end.
The closing should then become simpler: three or four priorities for the next 12 months, a clear forward-looking statement and a visual connection back to the opening story.
How long should an AGM presentation be, and when should you start?
AGM presentations ran from roughly 60 to more than 130 slides. There is no ideal count. It follows the number of funds, portfolio companies, speakers and sessions. Planning should begin four to six weeks out. For a 100-plus-slide annual general meeting presentation with several contributors, six to eight weeks is the realistic runway for design, reviews, late changes and QA. Most teams draft the AGM PowerPoint presentation in-house and bring design in late.
What belongs in the main deck versus the appendix?
Detailed company information, valuation methodology and supporting financial data belong in the appendix. Moving them out keeps the main AGM slides strategic and gives partners something to open when an LP presses.
What makes an AGM presentation work
The pattern is structural, not stylistic. Repeatable frameworks and clear hierarchy let LPs move from market context to performance to priorities without losing the story. For slide-level detail: AGM presentation tips and must-have slides, tight AGM deadlines, and multi-team AGM presentations.
Planning your annual meeting deck this year? Happy to review the outline with you before design starts.